Who taxes minerals: the 2026 mining amendment
LeadPrelims and MainsSeptember 2026
Why in news
The Act, passed in August 2026, has drawn protests in the Odisha Assembly, with mineral rich States saying it undoes a Supreme Court ruling in their favour.
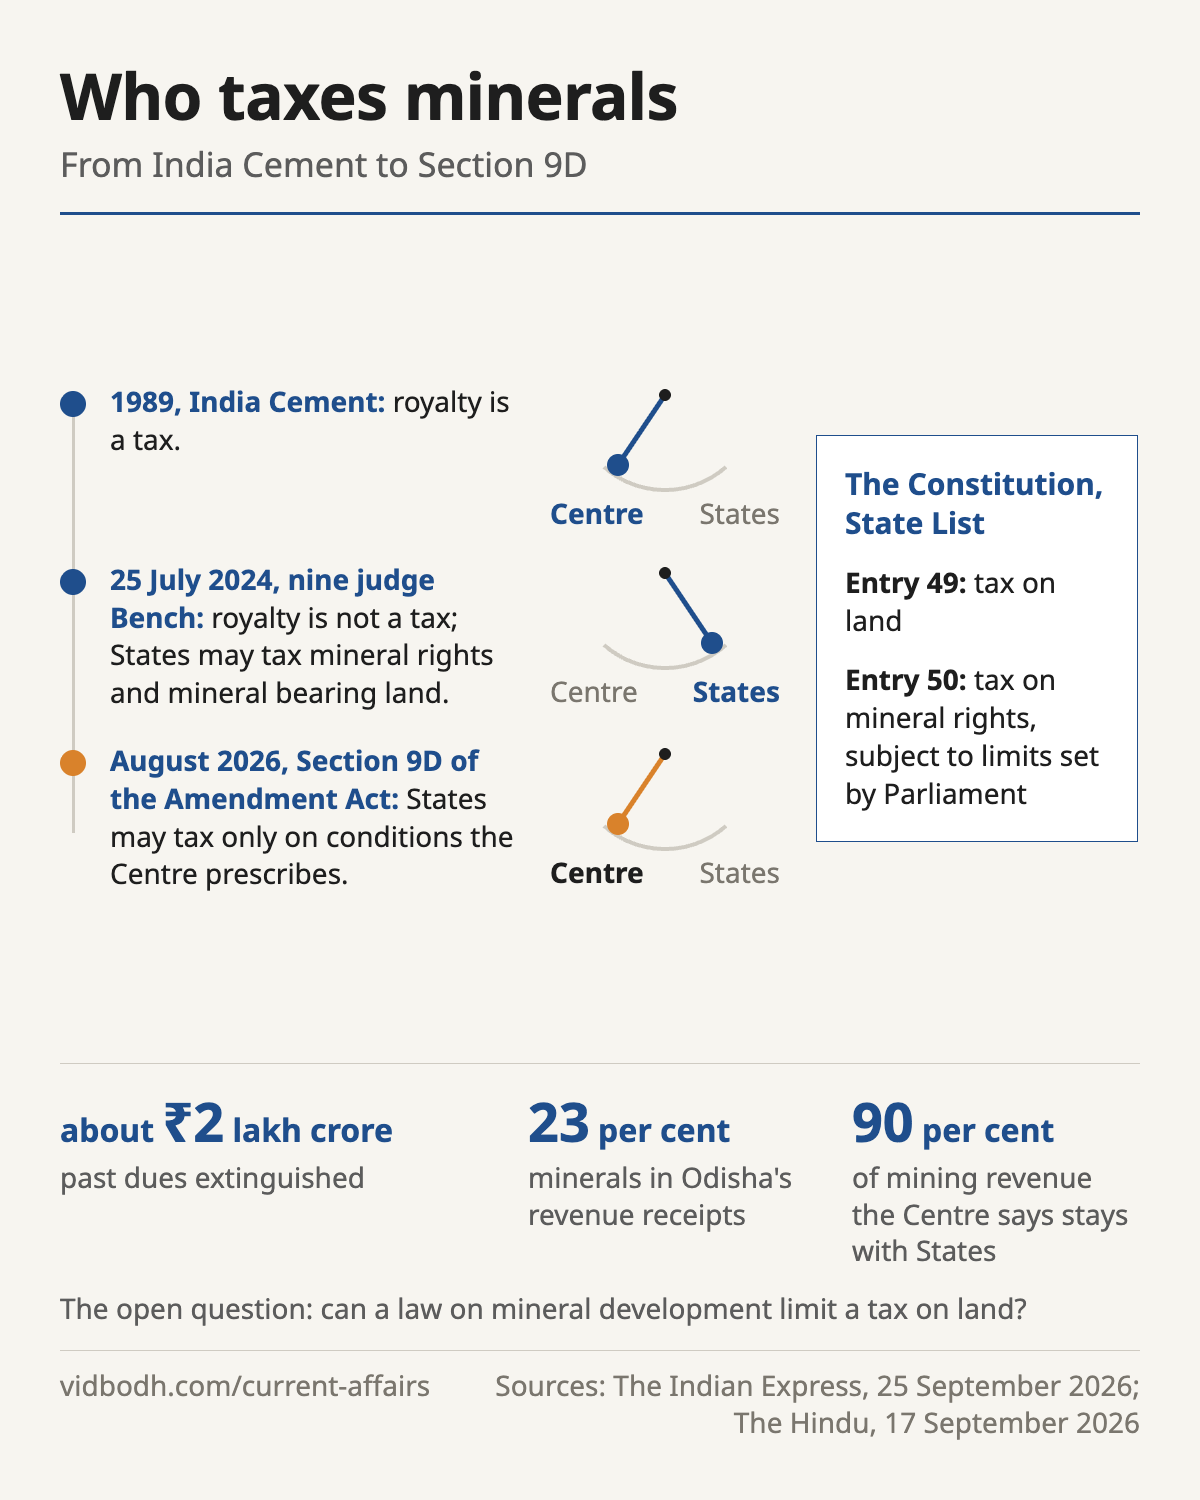
- about ₹2 lakh croreunpaid dues from earlier State levies that the Act extinguishes
- 23 per centshare of minerals in Odisha's revenue receipts
- 90 per centshare of mining revenue that the Centre says will still go to States
Background
- Entry 50 of the State List lets States tax mineral rights, subject to any limits Parliament sets by a law on mineral development; Entry 49 lets them tax land.
- In India Cement (1989) the Supreme Court held that royalty is a tax, which kept States out of the field.
- On 25 July 2024 a nine judge Bench, in Mineral Area Development Authority v. Steel Authority of India, overruled it: royalty is not a tax, and mineral bearing land falls within the States' power to tax land.
- That ruling allowed dues from before the judgment to be recovered in instalments over 12 years from April 2026.
What the Act does
- Section 9D bars States from levying taxes or cesses on mineral rights or mineral bearing land except on conditions the Centre prescribes.
- It extinguishes the unpaid dues from earlier levies, and the Centre plans a cap on combined levies after consulting the States.
The Centre's case
- A predictable tax regime is needed for long term investment in mining.
- Many levies on the same mineral raise its cost and feed into inflation, and industry says the law gives fiscal certainty.
The States' case
- The law overrides the 2024 ruling and leaves mineral rich States bearing the costs of mining without the fiscal room to meet them.
- Odisha's opposition puts the loss at ₹12,000 crore a year.
From India Cement to Section 9D
1989
India Cement: royalty is a tax, so States cannot levy it
25 July 2024
nine judge Bench: royalty is not a tax; States may tax mineral rights and mineral bearing land
April 2026
recovery of past dues in instalments was due to begin
August 2026
the Amendment Act adds Section 9D and extinguishes the dues
The two cases
The Centre
- a predictable regime for long term mining investment
- many levies raise mineral costs and inflation
- 90 per cent of mining revenue still goes to States
The States
- the 2024 ruling is nullified
- mining's costs fall on States without the revenue to meet them
- minerals are 23 per cent of Odisha's revenue receipts
The open question
- Entry 50 expressly allows Parliament to limit taxes on mineral rights, but Section 9D also reaches land, which the 2024 Bench placed with the States under Entry 49.
- Whether a law on mineral development can limit a tax on land is the constitutional point on which the amendment will be tested.
Prelims facts
- Royalty is not a tax: Mineral Area Development Authority v. Steel Authority of India, 2024, nine judges.
- India Cement, 1989 was overruled.
- A mineral bearing land tax is a State levy on land that contains minerals, charged per tonne of mineral.
- Entries 49 and 50 are in List II, the State List.
See also: District Mineral Foundations
Sources: The Indian Express, 25 Sep 2026: What does the Centre's new mining law say and why are states opposing it? (opens in a new tab) · The Hindu, 17 Sep 2026: Mining amendment is unfair to States (opens in a new tab)
Earlier coverage: MMDR Amendment Act, 2026 and the States' power to tax minerals · The monthly magazine, September 2026